The Pros and Cons of Buying New Construction Versus a Pre-owned House or Condo

Marci • December 10, 2014

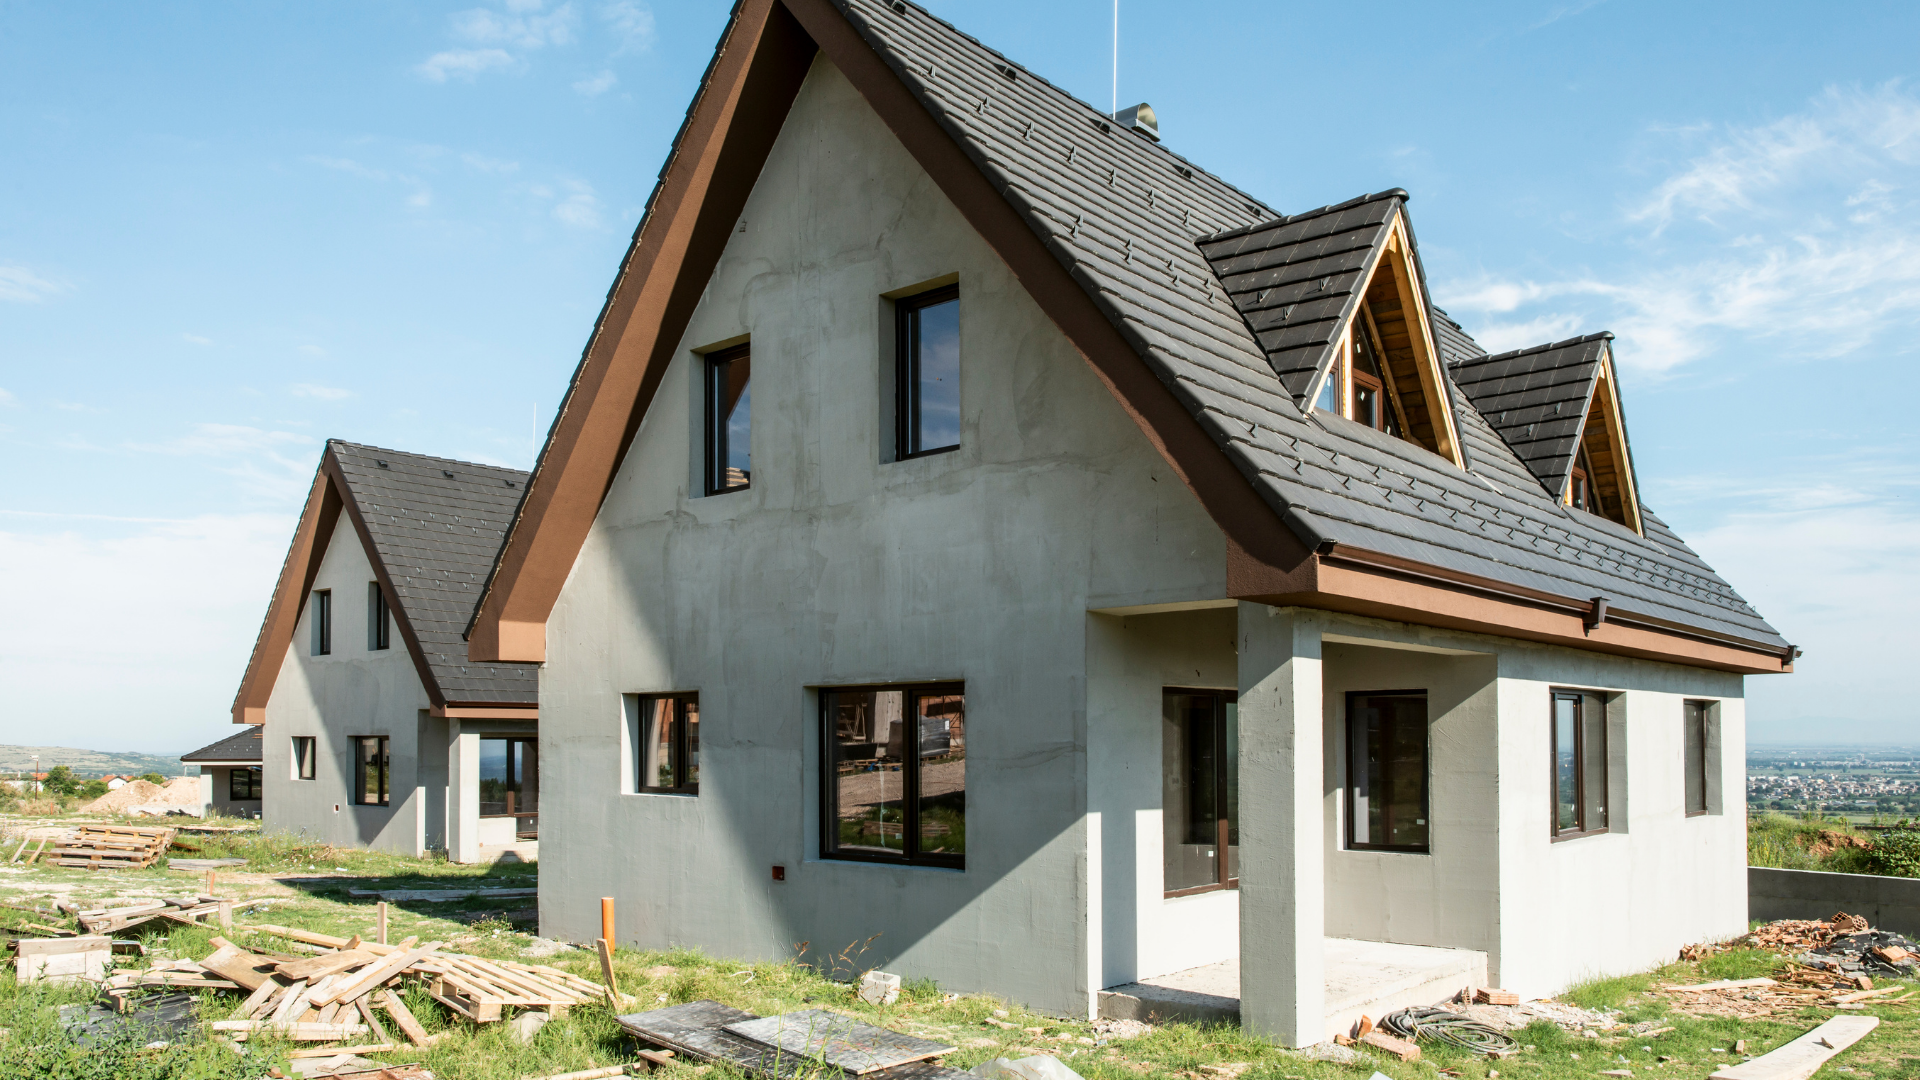
Whether you’re new to the Vancouver real estate market or you’re a seasoned veteran who is buying their third or fourth home, one of the major considerations you’ll need to make is whether you want to buy an existing pre-owned home or you want to buy something newly-built. In today’s post we’ll assess some of the pros and cons of buying a brand new home versus buying pre-owned including price differences, the need for renovations and more.

The Price Factor

For many homebuyers, price is a major deciding factor in the type and size of home that they end up purchasing. Here in Vancouver, in most cases you’ll find that pre-owned homes are less expensive than an equivalent piece of new construction. Of course, if you’re interested in buying a detached house on a sizeable piece of land you’ll end up paying far more for the ground under the home than for the home itself, so in this case a new house may be about the same price as an existing one.

Location, Location, Location

Location is another major consideration when buying a new home and this will impact whether or not you can buy something brand new. If you’re after a newly-built condo, you’ll be able to have your pick from many new buildings in Downtown Vancouver, North Vancouver, Burnaby, Richmond and Surrey. However if you’re looking for a new house, you may find that your options are more limited in these areas and you may need to expand your search to further out in the suburbs.

Customization vs. Renovation

Are you the type that likes to be able to select all of the fixtures and amenities that go into your home? If so, you’ll want to buy new as you can have your say before the home is completely finished. Conversely, if you’re a ‘do it yourselfer’ or you love the idea of having a number of renovation projects to keep you busy, you’ll prefer a pre-owned home.

What About the Warranty?

One of the major benefits of purchasing a brand new house or condo is that it will come with a warranty, typically lasting anywhere from five to ten years. Having a warranty on your home can be incredibly handy if a major structural item decides to give out or some other serious flaw is discovered. If you’re buying a pre-owned home you can typically get an after-market warranty but you’ll either end up paying out of pocket or you’ll have to convince the seller to cover this cost as part of the purchase agreement.

It doesn’t matter if you’re buying a brand new piece of Vancouver real estate or you decide to go with a pre-owned property, if you’re in need of mortgage financing to help secure the home, I can help. Contact me at your convenience and I’ll be happy to share my expertise to assist you with choosing the right mortgage.

Share

By Marci Deane • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Marci Deane • October 21, 2026
Why More Mortgage Options Matter—Especially for Assignment Purchases One of the biggest advantages of working with an independent mortgage professional is access to choice. Instead of being limited to one lender and one set of products, mortgage brokers work with multiple lenders—each with different guidelines, risk tolerances, and mortgage solutions. That flexibility becomes especially valuable when your situation doesn’t fit neatly into a “standard” box. A great example of this is purchasing new construction through an assignment contract . Why Assignment Purchases Can Be Challenging Assignment purchases are often viewed as higher risk by traditional lenders. Rather than declining these deals outright, many lenders quietly make them difficult by adding layers of conditions, restrictions, or uncertainty. This can lead to delays, frustration, or financing falling apart late in the process. The Good News There are lenders—available exclusively through the broker channel —that have clear, favourable policies for assignment purchases. With the right lender and proper planning, these transactions are absolutely doable. Typical Financing Requirements for Assignment Purchases While every situation is unique, many lenders that allow assignment financing look for the following: Standard purchase qualification, including income verification, credit, and down payment Assignments accepted at either the original purchase price or current market value Minimum 620 credit score , with no prior bankruptcies or consumer proposals The full down payment must come from the purchaser —seller incentives cannot be used Required Documentation To secure financing, lenders typically require: The original purchase agreement signed by all parties The MLS listing (if applicable) The assignment agreement signed by the builder, original purchaser, and new buyer Any side agreements outlining changes to the purchase price A full appraisal to confirm value This list isn’t exhaustive, but it highlights that while assignment purchases require more coordination, they are very achievable with the right lender and guidance. Final Thoughts Assignment contracts can open doors to great opportunities—but only if your financing supports the transaction. This is where access to multiple lenders and specialized policies makes a real difference. If you’re considering purchasing new construction through an assignment, or if you’d like to explore more traditional purchase options, feel free to connect anytime. I’d be happy to walk you through the mortgage products available and help you choose an option that doesn’t limit your financing possibilities.
By Marci Deane • October 14, 2026
How Mortgage Payment Frequency Affects What You Pay Over Time You’ve probably heard the saying that there are two certainties in life: death and taxes. When it comes to your mortgage, there’s really just one certainty—you’ll repay what you borrow, plus interest. What is flexible, though, is how often you make your mortgage payments. And that choice can have a meaningful impact on how quickly you pay down your mortgage and how much interest you pay over time. The Six Mortgage Payment Frequencies Most lenders offer the following payment options: Monthly – 12 payments per year Semi-monthly – 24 payments per year Bi-weekly – 26 payments per year Weekly – 52 payments per year Accelerated bi-weekly – 26 payments per year Accelerated weekly – 52 payments per year Standard Payment Frequencies The first four options are designed to align with how you get paid. For example: Paid monthly? Monthly mortgage payments may make sense. Paid every two weeks? Bi-weekly payments can align nicely with your cash flow. With these standard options, regardless of how often you pay, the total amount paid over the year is the same —it’s simply divided into more frequent payments. What Makes “Accelerated” Payments Different Accelerated payments work differently—and this is where the real savings happen. With accelerated bi-weekly or accelerated weekly payments, you’re paying a slightly higher amount each time. That extra money goes directly toward reducing your mortgage principal, which lowers the interest you’ll pay over the life of the mortgage. A Simple Example Let’s assume a $1,000 monthly mortgage payment: Monthly: $1,000 once per month = $12,000 per year Semi-monthly: $500 twice per month = $12,000 per year Bi-weekly: $1,000 × 12 ÷ 26 = $461.54 every two weeks = $12,000 per year Accelerated bi-weekly: $1,000 ÷ 2 = $500 every two weeks = $13,000 per year With accelerated bi-weekly payments, you effectively make two extra payments per year without having to think about it. Those extra payments reduce your principal faster, which lowers interest costs over time. Accelerated weekly payments work the same way—you just make smaller payments more frequently. Why This Matters Long Term While it’s difficult to calculate exact savings due to variables like interest rates, terms, and amortization changes, maintaining an accelerated payment schedule over the life of your mortgage can reduce your amortization by up to three years and save a significant amount of interest. The Bottom Line Accelerated payments are a simple, automatic way to lower your overall cost of borrowing—without needing to make lump-sum payments or drastically change your budget. If you’d like to see how different payment frequencies would impact your mortgage specifically, feel free to reach out anytime. I’d be happy to walk through the numbers with you and help you choose the option that fits your goals.